TinOne Announces Private Placement Financing of Units for Gross Proceeds of up to C$750,000
TinOne raises $750k at depressed prices amid going concern uncertainty.
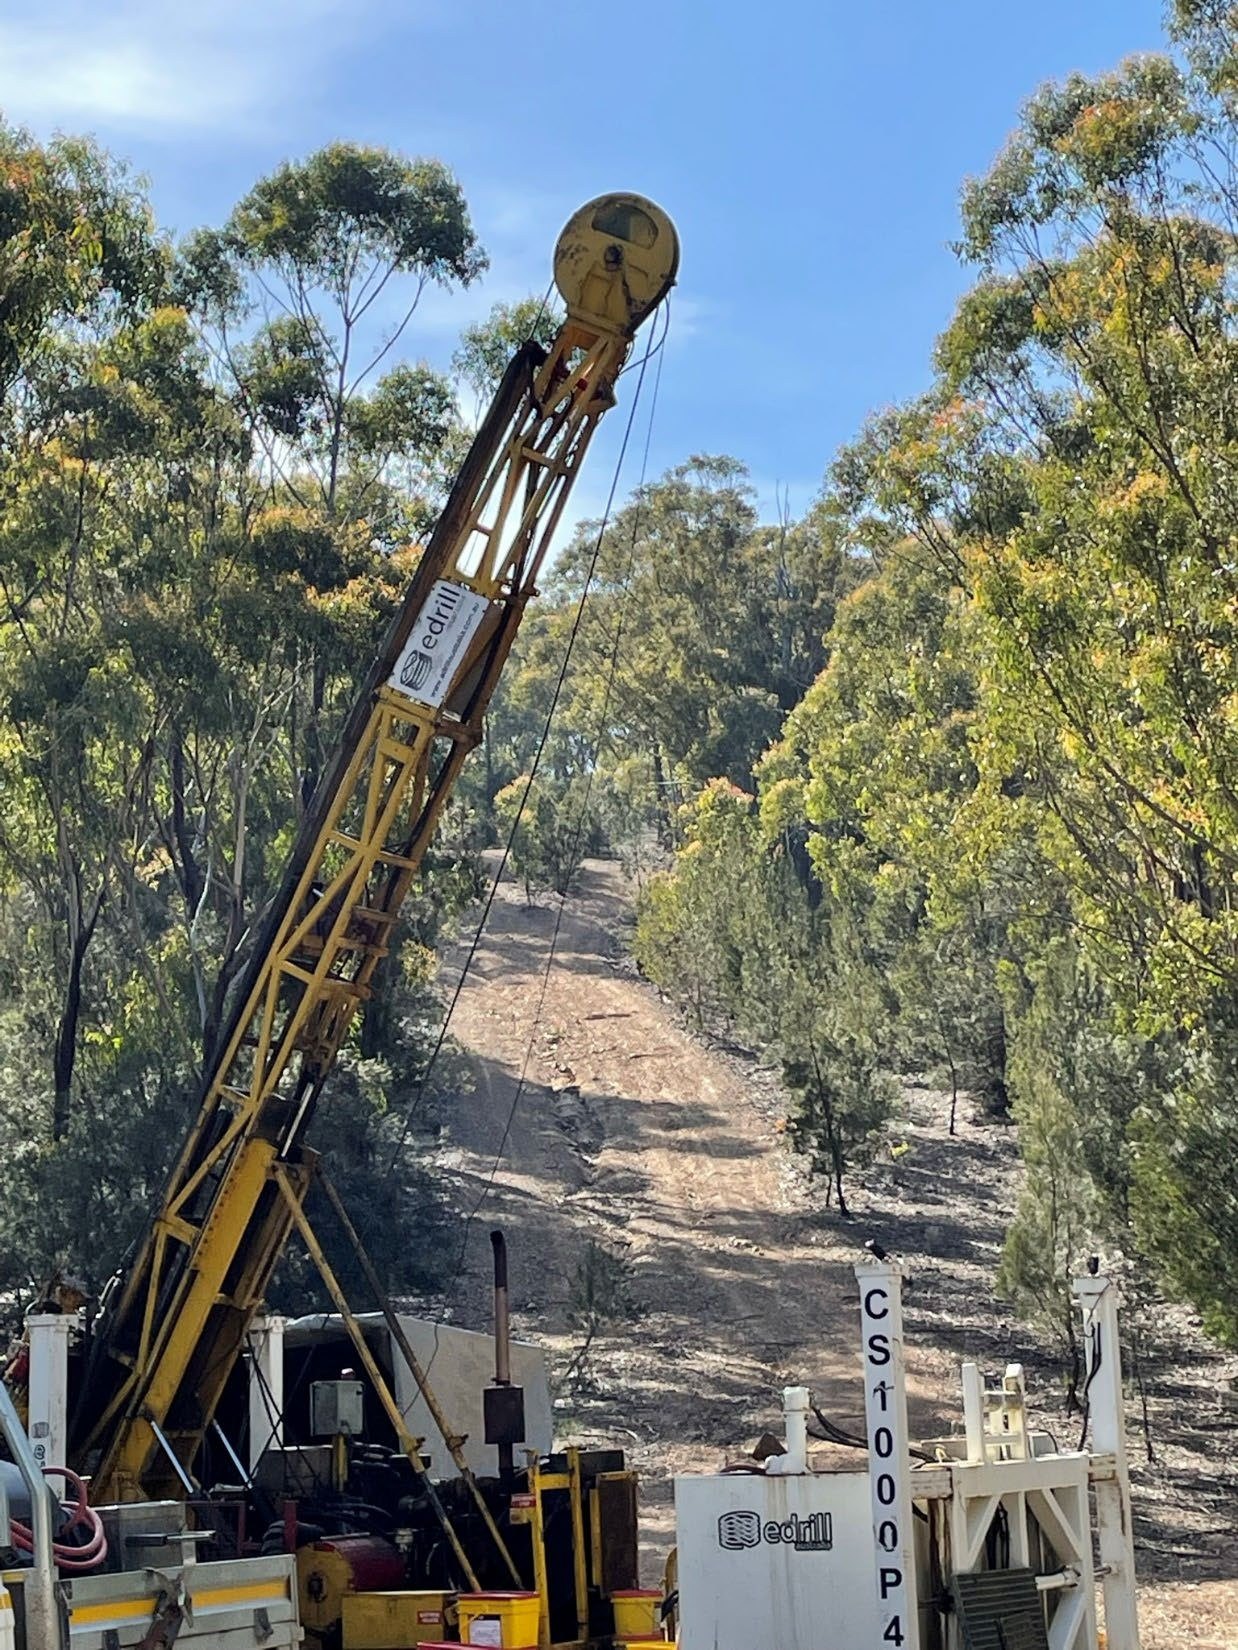
TinOne Resources Inc. announced a non-brokered private placement of up to 15,000,000 units priced at C$0.05 per unit, with gross proceeds capped at C$750,000. Each unit consists of one common share and one whole common share purchase warrant exercisable at C$0.10 for 24 months. The company intends to use the proceeds to fund advancement of its Tasmanian project and for general working capital. Finder’s fees of up to 6% in cash and 6% in warrants are permitted, and the securities carry a 4-month plus 1-day statutory hold period. Closing is subject to Board and TSX Venture Exchange approvals.
TinOne Resources Inc. (TORC) raised $750,000 through a financing deal that adds 15,000,000 new shares and warrants to the approximately 21.9 million shares currently outstanding. The issue price of C$0.05 aligns exactly with the current market price, reflecting the company's depressed valuation without a premium.
The amount raised is modest relative to the company's accumulated deficit exceeding $10.1 million and a working capital deficiency of $754,639. While the cash injection provides near-term liquidity, it does not resolve the material uncertainty regarding the company's ability to continue as a going concern. The issuance of warrants at C$0.10, which is double the issue price, adds further potential dilution upon exercise. This capital raise is expected by the market for a pre-revenue junior explorer facing liquidity constraints.
TinOne Resources Inc. (TORC) is a pre-revenue junior explorer focused on tin, lithium, and tungsten projects in Tasmania, Australia. Its flagship assets include the Great Pyramid Tin Project, which is 100% owned and holds an Inferred resource of 8.39 Mt @ 0.17% Sn, and the Aberfoyle Tin, Tungsten & Lithium Project, a historic producer with district-scale potential.
The company recently impaired several other projects, including Rattler Range, Castle Carey, and Vickory Creek, to concentrate capital on the two primary assets. Management emphasizes Tasmania as a tier-1, ESG-friendly jurisdiction with strong infrastructure and permitting efficiency. No economic studies, NPV, or IRR have been released, leaving the projects in the conceptual/exploration stage.